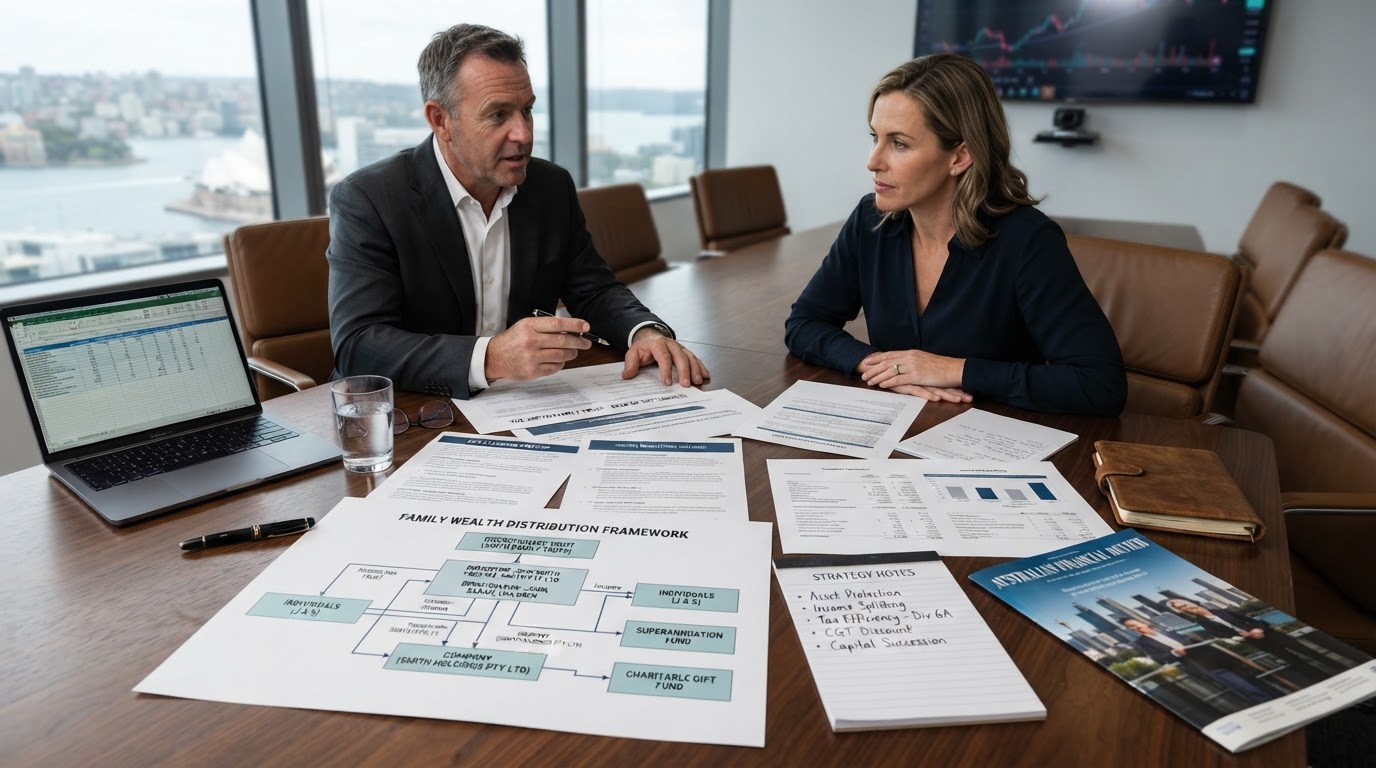
Discretionary Family Trusts: Wealth Structuring and Section 100A Rules
Understand how family trusts protect assets and distribute income tax-effectively, plus the ATO's Section 100A guidelines on adult-child distributions and reimbursement arrangements.
 Freedom Tax22 July 20266 min read
Discretionary family trusts are a cornerstone of Australian private wealth planning. Used well, a trust protects family assets from external creditors and lets the trustee distribute each year's income and capital gains to family members in the most tax-efficient way. Used poorly — particularly around distributions to adult children — the same flexibility attracts the ATO's close attention under Section 100A. The structure rewards a disciplined, documented approach and punishes a casual one.
The mechanics of family trust distributions
A trust itself does not pay income tax provided all net income is distributed to beneficiaries before 30 June. Each beneficiary then reports their share of trust income in their individual tax return and pays tax at their own marginal rate. The trustee's discretion lets each year's distribution be directed to whichever adult beneficiaries are in the lowest brackets — a powerful planning lever in years where one family member has unusually low income or an unused cap.
Where income is not fully distributed, the trustee is assessed on the undistributed amount at the top marginal rate. This makes a valid, written distribution resolution by 30 June non-negotiable. The resolution must be consistent with the trust deed and retained with the trust's records; an oral resolution, or a resolution made after 30 June, will not be recognised.
ATO Section 100A: what you must know
Section 100A targets reimbursement arrangements — broadly, where trust income is appointed to an adult child or low-tax beneficiary but the economic benefit of the distribution is retained or redirected to the parents or another beneficiary. The ATO's compliance approach (set out in Taxation Ruling TR 2022/4 and Practical Compliance Guideline PCG 107) applies increased scrutiny to these arrangements, and to distributions that look like ordinary family dealing but lack genuine economic substance.
To stay within the ordinary family dealing exception, a distribution should reflect a genuine transfer of the economic benefit of the income to the named beneficiary — control over and use of the funds — not a paper appointment followed by an immediate return of the money to the trustee or the parents.
Beneficiary loan accounts and present entitlements
Where a beneficiary becomes presently entitled to trust income but the cash is not immediately paid, a beneficiary loan account (unpaid present entitlement) arises. That account must be properly documented, bear interest where required, and be repaid or otherwise dealt with in line with the trust deed and Division 7A where a company beneficiary is involved. Loan accounts that accumulate indefinitely without genuine repayment attract ATO scrutiny and, in some cases, can be taxed in the beneficiary years later.
Building a defensible distribution plan
- Resolve distributions in writing on or before 30 June each year, within the trust deed's powers
- Ensure the named beneficiary genuinely receives and controls the economic benefit of the distribution
- Document beneficiary loan accounts with terms, interest, and a repayment plan
- Avoid circular funding or round-tripping of distributed amounts back to the trustee or parents
- Review the trust deed every few years to confirm it still serves the family's current structure
A family trust is only as strong as the documentation behind it. Freedom Taxation prepares annual distribution resolutions, manages beneficiary loan accounts, and reviews each distribution against Section 100A and the trust deed before 30 June — so the trust delivers the tax efficiency it was established for without exposing the family to the ATO's reimbursement-arrangement focus.
Related articles
EOFY Tax Planning: Your Essential 30 June Checklist
The critical tax strategies to implement before midnight on 30 June — bringing forward deductions, super contributions, prepayments, trust distributions, and stock write-offs.
Read article
Australian Tax Return Guide: Deductions, Lodgment Dates and ATO Rules
A complete guide to lodging your Australian individual tax return — key ATO deadlines, allowable work deductions, the Medicare levy, and lodgment options through a registered tax agent.
Read article
Capital Gains Tax in Australia: The 50% CGT Discount and Property Rules
How Capital Gains Tax works in Australia, qualifying for the 50% CGT discount on assets held over 12 months, main residence exemptions, and the 6-year rule.
Read article